Intercompany FX Settlement Between Subsidiaries
Coordinating subsidiary payments cuts hidden FX costs and reduces audit risk.
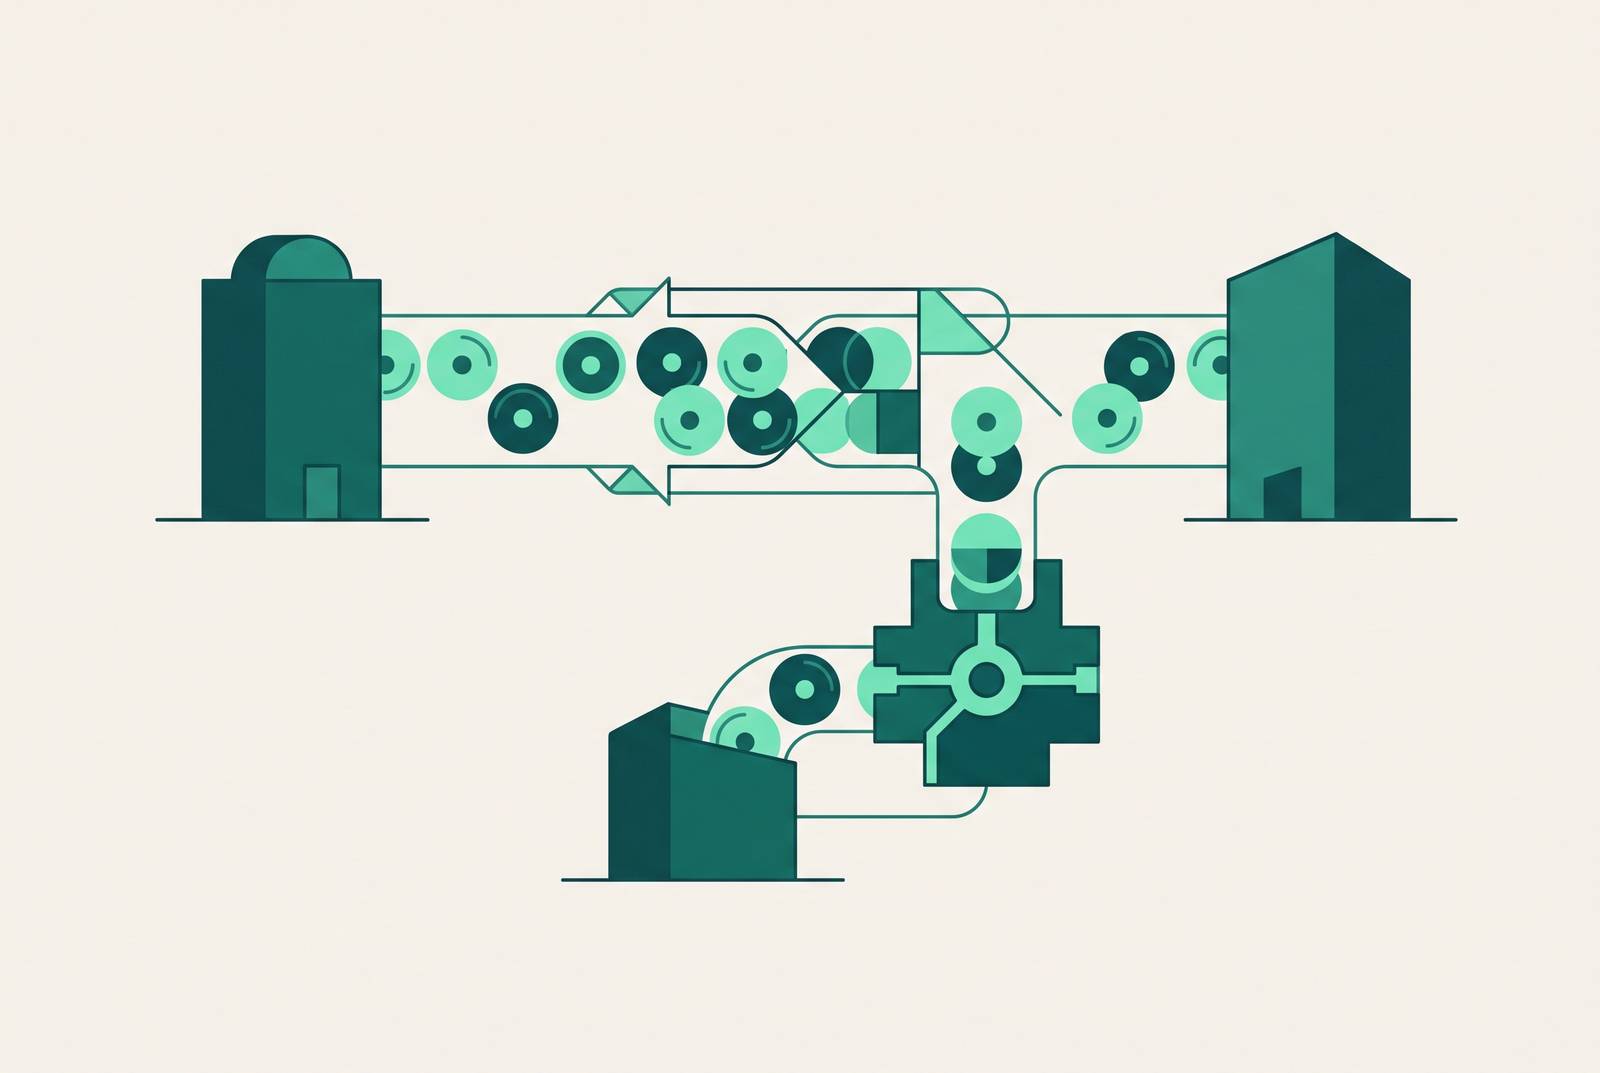
An intercompany transfer moves funds between legal entities that share common ownership. That's a distinct thing from the intercompany transaction itself, the invoice, the loan, the management fee, that created the obligation. The distinction matters because most groups treat the transfer as an afterthought, a wire that just needs to happen, when it's actually where the money leaks out.
Common ownership doesn't mean common anything else. A subsidiary in one country and a subsidiary in another might sit under the same parent company, but they still report in different functional currencies, answer to different tax authorities, bank with different institutions, and operate under different regulatory regimes. So a payment from a parent to a subsidiary, or between two subsidiaries, touches treasury, tax, accounting, compliance, and foreign exchange before the funds land anywhere. Every one of those triggers costs money in ways the wire fee never shows.
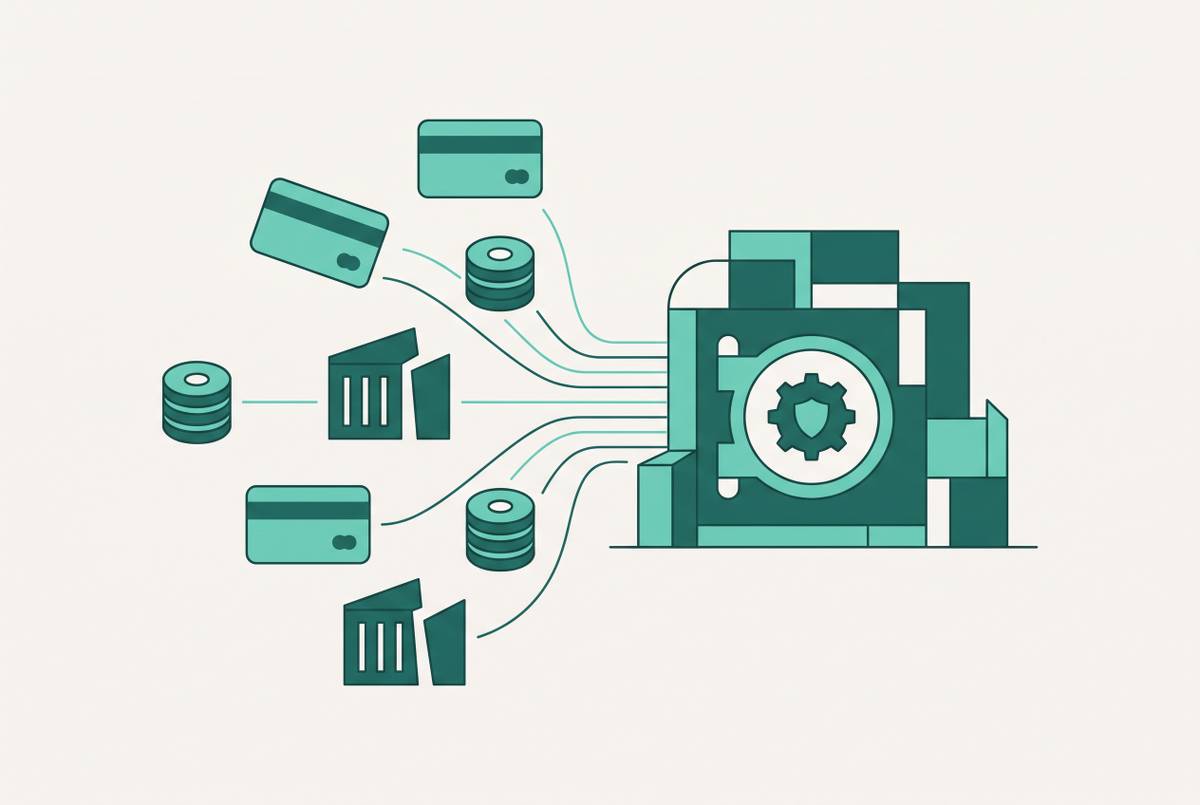
That's the part groups miss. The visible cost, the flat wire fee a bank quotes, is the smallest piece of the bill. The sending bank applies its own FX spread on the conversion. Additional charges can accumulate along the payment route. The receiving bank charges again on the way in. The money that arrives ends up meaningfully less than what left, and almost nobody runs that comparison before hitting send.
Where value leaks when subsidiaries settle ad hoc
Four failure modes compound each other when there's no central process governing how subsidiaries settle with each other.
The first is unmanaged FX exposure. Each subsidiary settles its own invoices on its own schedule, and each one of those settlements triggers a separate currency conversion at whatever rate the local bank happens to offer that day. Nobody is comparing rates across the group, nobody is timing the trades, and nobody is aggregating volume to get better pricing. It's dozens or hundreds of small, uncoordinated conversions instead of one large, planned one.
The second is liquidity sitting idle for no reason. Without a real-time view into what cash the group actually holds and where, subsidiaries build precautionary buffers, holding more cash than they need, or worse, drawing on external credit lines they didn't need to touch. Both choices destroy yield. Cash sitting in a low-yield local account while another subsidiary in the same group pays interest on a credit facility is not a hypothetical inefficiency; it's the default outcome of not having visibility.
The third is reconciliation drag. Decentralized, manual settlement means somebody, usually several somebodies, is chasing down mismatches between what one entity booked and what another entity received. This gets worse when functional currencies differ, since a payment booked in EGP and received in SAR won't tie out cleanly without a translation step, and errors occur during that translation step. Close cycles stretch out because of this, month after month.
The fourth is regulatory and tax exposure, and this is the one with real teeth. Ad hoc processes tend to produce incomplete documentation, inconsistent transfer pricing across similar transactions, and intercompany interest calculations that don't match the terms on paper (if terms were even written down). Consider a parent that consolidates in AED, with a Subsidiary A in Egypt selling to a Subsidiary B in Saudi Arabia. Subsidiary A books EGP 5 million in revenue. Subsidiary B books SAR 600,000 in cost. When both get translated into AED for consolidation, the elimination entry produces a residual FX difference sitting at the gross margin level. Whether that residual belongs in other comprehensive income or in the P&L is a live debate among IFRS practitioners as of mid-2025, and groups without a documented policy on this get inconsistent answers depending on which accountant is closing the books that quarter.
The tax stakes are not abstract. Under IRC §6662(e), a transfer pricing adjustment equal to the lesser of $5 million or 10% of gross receipts triggers accuracy-related penalties running from 20% to 40% of the adjustment amount under IRC §6662(e). Penalties on these adjustments run from 20% to 40% of the amount in question. An intercompany agreement isn't paperwork for its own sake, it's a required piece of that documentation defense.
None of these four problems is the headline. The real cost of doing this badly is operational drag, wasted liquidity, and audit exposure stacking on top of each other simultaneously, not the FX spread, and that's what makes the case for fixing this a risk argument first, a cost argum... The real cost is operational drag, wasted liquidity, and audit exposure stacking on top of each other simultaneously, and that's what makes the case for fixing this a risk argument first, a cost argument second.
How intercompany netting eliminates most of the conversion waste
FX netting takes multiple intercompany payments and collapses them into one net payment. Instead of Subsidiary A wiring Subsidiary B while Subsidiary B wires Subsidiary A back, in the same week, in different currencies, the two obligations offset each other and only the difference actually moves.
The effect cascades. Fewer transactions means fewer FX conversion events, and each conversion that does happen is larger and more predictable, which gives treasury actual pricing leverage with its banks, leverage that doesn't exist when trades are scattered and small.
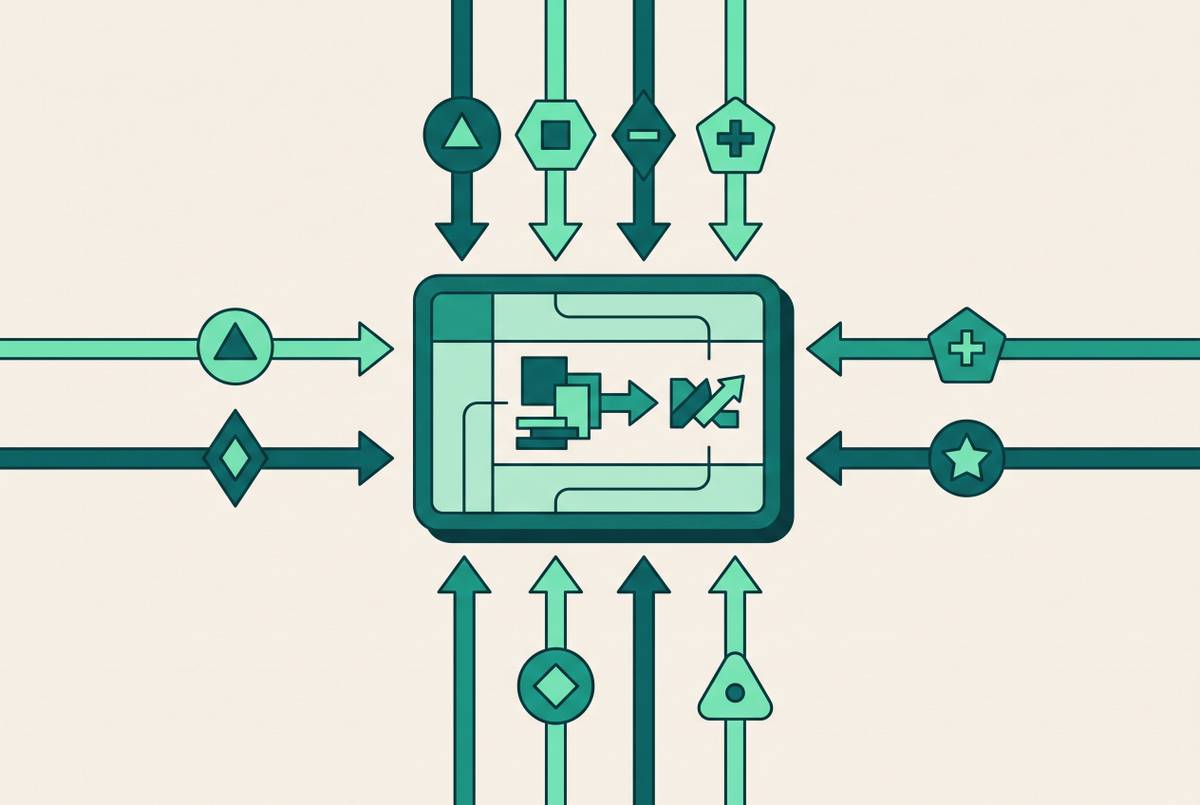
The mechanics run in a fairly consistent sequence. Subsidiaries submit their intercompany invoices into a netting system, and receivables get matched against payables automatically under rules set up in advance. The system then calculates a net position for each entity, a single number owed or due. Before anything settles, a compliance gate checks the amounts against transfer pricing policy, tax approvals, and whatever authorization hierarchy the group has set. Only after that gate does settlement happen, and for most entity pairs, nothing physically moves. Cash only changes hands where a genuine net difference remains.
The upside appears directly in transaction count. Groups that implement netting can cut cross-border transfers by up to 70%, a structural change in how often the group touches the FX market rather than a marginal improvement.
What an in-house bank does that netting alone cannot
Netting reduces the number of conversions. An in-house bank, or IHB, goes further and restructures who does the converting.
An IHB is an internal treasury function that acts like a central bank for the group's own entities, clearing payables and receivables between them. It doesn't need a banking license or a regulatory filing to operate, it's a capability the group builds internally, not a legal entity in the traditional sense.
Currency obligations between affiliates settle directly on the IHB's internal ledger, so cash never physically moves for positions that offset each other, cashless settlement in the fullest sense. Currency obligations between affiliates settle directly on the IHB's internal ledger, so cash never physically moves for positions that offset each other, cashless settlement in the fullest sense. The IHB then aggregates whatever exposure is left across every subsidiary and executes that residual as one bulk FX trade with external banks, and volume like that gets pricing no single subsidiary could negotiate on its own. Internally, the IHB applies its own hedge rates to each subsidiary, which keeps intercompany FX pricing aligned with both group treasury policy and transfer pricing rules at the same time, rather than treating those as two separate problems. Group treasury gets a real-time, consolidated view of positions, balances, and exposure across the whole group, which removes the information gap that used to force subsidiaries to hoard cash defensively. On the reporting side, subsidiaries receive virtual FX statements, and intercompany accounting entries for FX adjustments get generated automatically rather than reconstructed by hand at month end.
Larger groups sometimes build this out regionally, running separate hedging hubs for EMEA, APAC, and the Americas to match local regulation and time zones. The IHB structure accommodates that without losing central control, the regional hubs report into the same governance, they just execute closer to where the exposure sits.
Netting and the IHB together handle where the money settles and how it clears. What's left after that is a strategy question: what happens to the exposure that survives all of this offsetting.
Hedging the residual: what group treasury does after netting
After bilateral positions offset each other, real currency mismatches remain, and they tend to concentrate inside the IHB rather than spread thin across individual subsidiaries. That concentration is actually useful. It means one team is deciding how to hedge one number, not fifty entities each making their own call.
Central treasury collects the transaction data, checks the figures, and calculates the net position, then decides when to trade and what instrument to use, rather than letting each subsidiary convert currency whenever its own cash flow happens to demand it. That timing control is worth more than it sounds. Instead of dozens of subsidiaries converting at whatever rate the market offers on whatever day they happen to need cash, group treasury can batch conversions or lock in forward rates on its own schedule, which cuts down both rate variance and the sheer number of times the group touches the market.
Intercompany loans deserve their own mention here, because the standard hedging approach for them is quietly expensive. The typical setup rolls a one-year FX hedge over annually. That carries a real cost, cost of carry on these rollovers can run as high as 10%, and it leaves the position exposed during the gap between when one hedge expires and the next one gets put on. Worse, mark-to-market swings create real cash problems: a hedge that moves against the group triggers a margin call, actual cash out the door, while a hedge that moves in the group's favor sits there as a paper gain that generates no cash. That asymmetry is a liquidity trap dressed up as a hedging strategy.
The better structure uses a swap instead, where the near leg supplies the funding liquidity the loan actually needs and the far leg hedges the balance sheet exposure. Structured that way, the group avoids the annual roll cost and sidesteps the mark-to-market asymmetry that makes the traditional approach so punishing.
Transfer pricing and documentation as non-negotiable guardrails
Intercompany agreements are binding contracts between related entities, and under IRC §482 and the OECD Transfer Pricing Guidelines, they serve as the primary evidence of what the group actually intended a transaction t... They are binding contracts between related entities, and under IRC §482 and the OECD Transfer Pricing Guidelines, they serve as the primary evidence of what the group actually intended a transaction to look like, pricing, risk allocation, payment terms, all of it.
Without them, tax authorities are free to recharacterize the transaction entirely, reallocate income between entities as they see fit, and apply accuracy-related penalties running 20% to 40% of the adjustment under IRC §6662(e). The automatic trigger kicks in at an adjustment of $5 million or 10% of gross receipts, whichever is smaller, and once that threshold is crossed, the 20% penalty applies unless the group already has contemporaneous documentation on file, which existed at the time of the transaction, not assembled afterward when the audit letter arrives.
This is where the netting and IHB structures described earlier either earn their keep or don't. The compliance gate built into the netting cycle, the checkpoint that verifies pricing methodology and approval before a settlement finalizes, is where this protection actually gets enforced. Documentation retrofitted after the fact doesn't carry the same weight with an auditor as documentation that was built into the process from the start.
How technology is changing what this framework can do
Modern treasury platforms now automate exposure collection, netting calculations, hedge execution, settlement, and reporting end to end, cutting down manual work and the errors that come with it, while giving treasury teams a live dashboard instead of a monthly spreadsheet reconciliation.
AI is layering on top of that baseline. Platforms are adding AI-assisted exposure mapping, automated hedge proposals, and anomaly detection, which shifts treasury from reacting to problems after the fact toward catching them before they compound. One practical use case: AI can surface natural hedges buried across a portfolio, offsetting exposures in different currencies or entities, that a manual review would likely never catch simply because nobody has time to cross-reference that many positions by hand.
Kyriba, at its KyribaLive 2026 event, introduced AI-orchestrated treasury tools that bring together stablecoin settlement through Circle, money market investing through J.P. Morgan Asset Management, and FX and liquidity planning inside one governance-driven platform. Customers reported meaningful reductions in liquidity planning time, and improving cash yield by as much as $2.07 million annually.
HighRadius, positioned by Gartner as a Challenger in Financial Close and Consolidation Solutions, claims 30% faster intercompany settlements and 95% accuracy on intercompany eliminations, with over 60% of close tasks automated through more than 200 LiveCube agents, and a stated target of 90% close automation by 2027.
Building the framework: a practical sequence for moving from ad hoc to controlled
None of this happens in one move. Most groups can't stand up an in-house bank and roll out AI-orchestrated hedging in the same quarter, and trying to do both at once is usually how these projects stall out. Getting the sequencing right makes a framework stick, while getting it wrong causes it to be abandoned halfway through.
Start by mapping and classifying before touching the process. Audit every intercompany relationship the group has: what flows between which entities, in which currencies, on what frequency, under what agreement, if any agreement exists. Classify each transfer by purpose, invoice settlement, loan, dividend, management fee, before picking a settlement method for it, since the classification is what drives the tax treatment and the documentation that will be required down the line. And find where hidden transactional FX is already buried in costs today. That number, ugly as it might be, is the baseline every later stage gets measured against.