Notional Pooling vs Physical Cash Pooling for Global Entities
Notional pooling nets balances on paper; physical pooling sweeps actual cash into a central account.
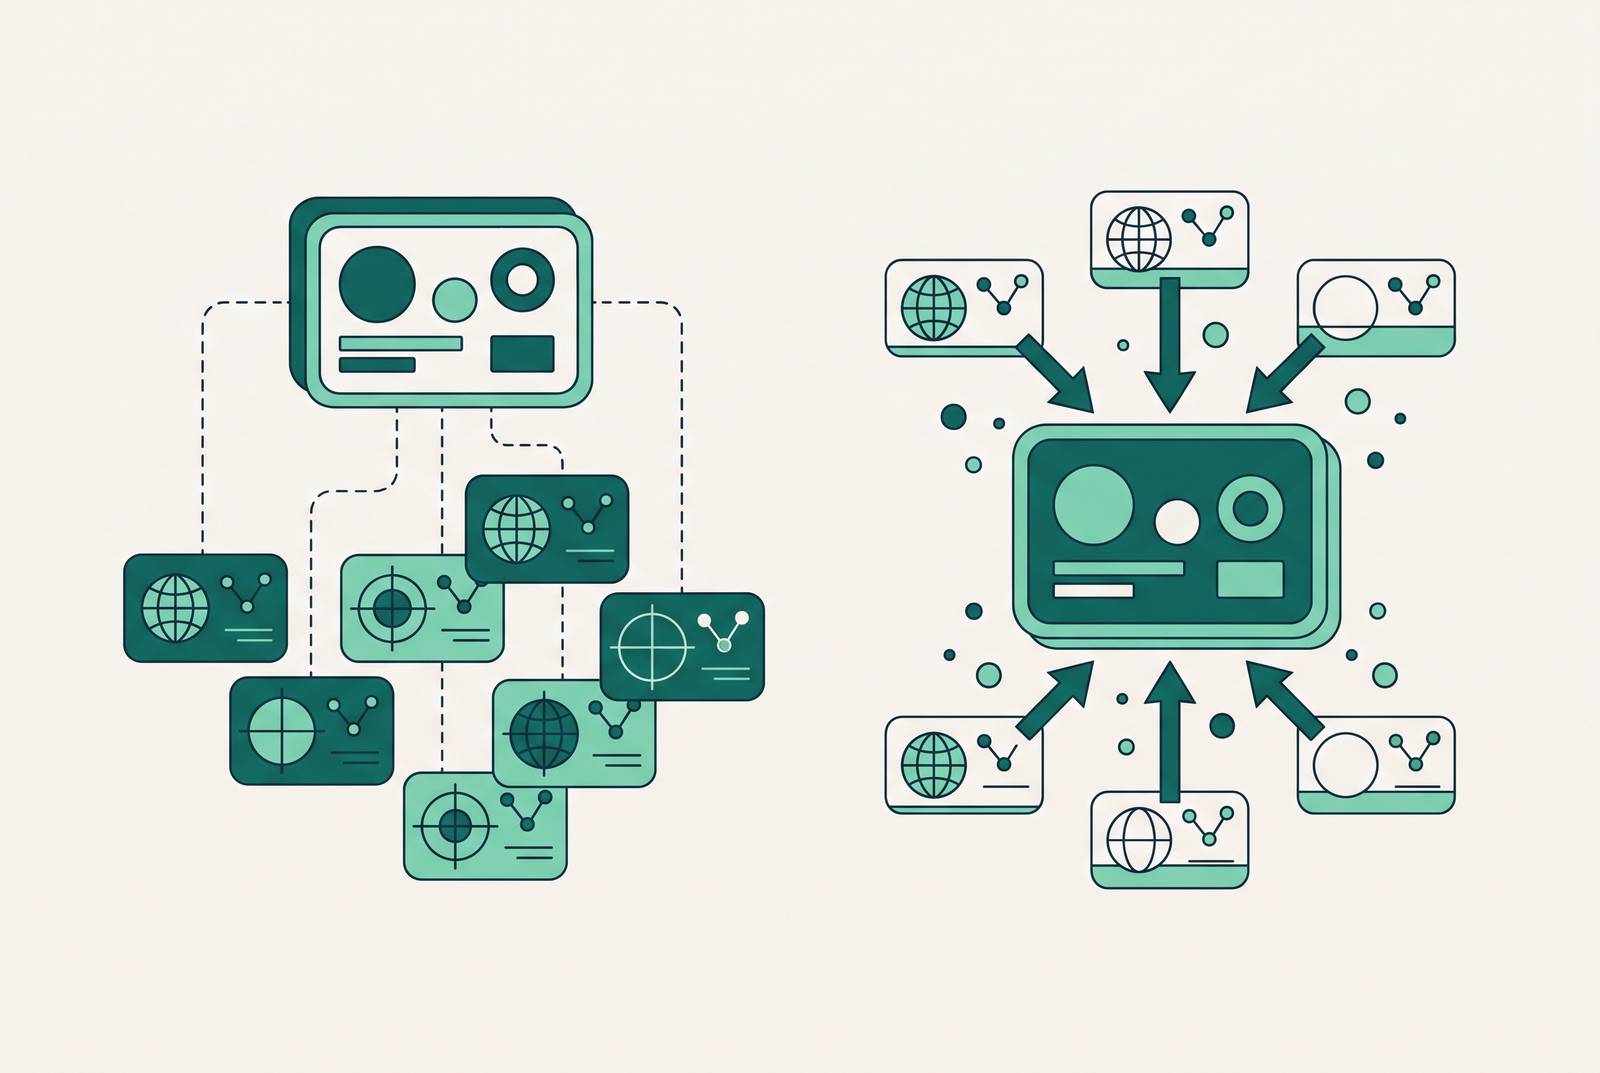
Cash sitting in forty different bank accounts across twenty currencies stays idle because nobody at treasury can see it in one place fast enough to put it to work. It's idle because nobody at treasury can see it in one place fast enough to put it to work. That's the problem cash pooling exists to solve, and two structures do the job in fundamentally different ways: notional pooling, which nets balances on paper without moving a dollar, and physical pooling, which actually sweeps cash into a central account. According to Intuit, 83% of large businesses now pool cash at a regional or global level, so this isn't some niche treasury trick, it's standard practice. And per KPMG, an estimated 60% to 80% of global trade runs through intercompany transactions. Getting the pooling structure wrong therefore costs real money at scale. Choosing between the two is a structural decision, shaped by where an entity operates, how it's governed, and what its bank can actually support. It's a structural decision, shaped by where an entity operates, how it's governed, and what its bank can actually support.
How notional pooling works without moving a dollar
Notional pooling takes the balances sitting in accounts across different entities and currencies and nets them into a single position, purely as a calculation. Nothing physically moves. Each account stays exactly where it is, legally owned by whichever entity holds it, and the bank builds what amounts to a shadow ledger that aggregates everything for the purpose of computing interest.
That's the whole trick: interest gets calculated and paid, or charged, on the net consolidated figure rather than on each account in isolation. When multiple currencies are involved, the pooling bank runs a short-dated swap to bring everything to a common basis, usually EUR or USD, before it calculates the net interest offset.
Because no funds actually cross a border, notional pooling sidesteps most of the cross-border withholding tax questions that come up when interest payments move between entities in different countries. That single fact makes it attractive to decentralized organizations. A subsidiary in, say, one jurisdiction keeps full control of its own account and its own cash, yet the group as a whole still gets the benefit of netting that subsidiary's surplus against another unit's deficit somewhere else. Paired with cash concentration tools, notional pooling can run this consolidation automatically near end of day, keeping operational accounts at target or zero balances without a treasury analyst manually pushing funds around.
How physical pooling works and what it demands from the accounting team
Physical pooling, often called cash concentration, works the way it sounds. Sub-account balances sweep into a central header account on a set schedule, daily, weekly, or monthly, and the header account takes actual legal ownership of that cash. Every single sweep is booked as an intercompany loan between the header entity and whichever subsidiary just had its cash swept out.
Sweeps can stay within one country or cross borders, and where currencies differ, an FX conversion component (Bank of America, for instance, documents this as part of its pooling offering) handles the exchange at a fixed, transparent rate. The upside of moving actual cash is a clean audit trail: every transfer appears in bank records, which makes life easier during a regulatory review or a tax audit.
The cost appears on the accounting side. Every sweep needs a journal entry recording the due-to and due-from balances between entities, and someone has to track arm's-length interest on each of those intercompany loans, day after day. Loan documentation for the pool structure has to be drafted before the arrangement even goes live, not after. And in a pool running daily sweeps across a dozen entities, the sheer volume of cross-border interest payments means each one potentially needs its own withholding tax review. Despite all that overhead, physical pooling remains the most widely used structure, largely because centralized corporations value direct control and a visible paper trail more than they mind the administrative load.
Where each structure fits: the variables that tilt the decision
Corporate governance is the first variable to check: a decentralized group, where subsidiaries need to keep running their own show, fits notional pooling naturally, since nothing about local autonomy changes. A decentralized group, where subsidiaries need to keep running their own show, fits notional pooling naturally, since nothing about local autonomy changes. A centralized treasury function that wants maximum control over where cash physically sits will lean toward physical pooling instead.
Currency exposure matters too, just in different ways for each structure. Notional pooling handles multi-currency netting at the bank level, cutting down on how many separate FX trades a treasury team has to execute. Physical concentration, when it includes an embedded FX conversion leg, can manage that same currency exposure through the sweep mechanism itself.
Intercompany complexity is where the gap widens fast. Physical pooling produces intercompany loan entries in volume, and that volume scales directly with the number of entities in the group. Notional pooling never creates that problem in the first place, since the bank just credits or debits each account and there's no loan to book. KPMG (June 2025) states that using intercompany term loans as a workaround "can quickly lead to an unmanageable number of intercompany transactions as the number of entities involved grows."
Banking relationships decide what's even possible. Notional pooling only exists where the group's bank can actually offer it, full stop, so the choice is constrained by infrastructure before it's constrained by preference. Physical pooling is more flexible on this front, since automated links can pull in third-party regional banks for subsidiaries that need to keep a local banking relationship for regulatory or practical reasons.
The stakes here aren't abstract. A Citibank study cited by Intuit found that large companies, in the $1 billion to $5 billion revenue range, that pool cash saw 23% higher return on invested capital and 27% higher return on equity than peers that didn't. The gain is real regardless of which method a company picks. How much of it actually gets captured depends on whether the structure matches the operating model.
Regulatory geography by method and jurisdiction
Notional pooling simply isn't available to entities domiciled in the United States. Legal and regulatory restrictions rule it out entirely, no exceptions. China closes the same door for a different reason: its banks can't offset debit and credit balances across accounts, so physical pooling executed through actual fund sweeps is the only real mechanism available there.
That creates an awkward asymmetry for any group with meaningful operations in both countries. There's no single pooling structure that can cover a given country's. and China footprint at once, so the regulatory map, not preference, decides the starting point.
EMEA remains the deepest, most established region for notional pooling, and three cities anchor it. London offers double taxation treaties with more than 100 countries, a full global currency offering, and sits five hours ahead of EST. Amsterdam brings treaties with 95-plus countries and a Eurozone base, six hours ahead of EST. Dublin, with treaties covering 78 countries, five hours ahead of EST, rounds out the group as a smaller but established option.
Bank of America's guidance on choosing a pooling location points to a handful of practical factors. Time zone affects end-of-day optimization outcomes: EMEA effectively works as a follow-the-sun hub linking an APAC pool to a European one, and even a one-hour gap between London and Amsterdam cut-off times can shift those outcomes. Currency breadth matters, since a hub offering more currencies natively lets a group consolidate more of its footprint into a single pooling location. Bilateral tax treaties cut down the administrative grind of reclaiming withholding tax on cross-border payments. And keeping accounts already established at a currency hub avoids the delay of opening new accounts across several jurisdictions just to build the pool.
Not every market plays along, either. Some jurisdictions require physical local accounts for tax and regulatory reasons, which rules out full notional consolidation unless the group builds in an alternative, such as a regional in-house bank hub.
Why hybrid structures are often the real-world answer
Global groups rarely fit neatly into one bucket, so most end up running a hybrid: physical sweeps in the regions or entities where regulation demands it, notional netting layered on top for everything else. The pattern usually looks like this: subsidiaries in jurisdictions that allow physical sweeps push funds into a regional header account, and that header account then joins a notional pool at the global level, avoiding cross-border fund movement anywhere it would be regulatorily painful or tax-inefficient.
That layering lets decentralized subsidiaries stay inside a group-wide liquidity structure without giving up local account control, since the notional layer sits above the physical sweeps rather than replacing them. Bank of America's overlay solution works this way: a notional pool held with one bank, while underlying accounts stay with third-party providers and sweep automatically into the centralized notional structure.
None of this runs on spreadsheets. Coordinating two pooling structures at once, tracking which entities feed which layer, requires a treasury management system built for it, plus tight coordination between treasury and every banking partner in the chain. With more entities and currencies involved, TMS automation moves from a nice-to-have to the only thing standing between the treasury team and a reconciliation nightmare.
An in-house bank model often complements the hybrid setup well. It centralizes liquidity management, cuts out manual intercompany tracking, standardizes how funding moves between entities, and can shrink the number of external bank accounts the group has to maintain, which matters most in markets where local regulation forces a physical account to exist anyway.
Transfer pricing obligations that apply to both structures
Neither structure gets a pass on transfer pricing. Cash pooling counts as a financial transaction under the OECD Transfer Pricing Guidelines. Arm's-length pricing on intercompany interest is a requirement. KPMG notes that tax authorities have sharply increased scrutiny of intra-group financial transactions since Chapter X was published, and a single adverse ruling in one jurisdiction can erase years of group profit.
Chapter X, part of the OECD's Transfer Pricing Guidelines for Multinational Enterprises and Tax Administrations, spells out how this analysis has to run. The first question is always whether the functions performed and risks carried by each party justify separate remuneration, or whether the pool leader is just performing an administrative role. In a notional pool, the header entity generally acts as an agent connecting participants to the bank, so its remuneration has to match that limited function. It can't simply pocket the full interest spread and call it a day.
Auditors tend to zero in on the same handful of red flags: interest rates set artificially low or at zero, arrangements that look like disguised profit distributions or capital contributions, thin capitalization from excessive intra-group borrowing, and permanent establishment questions if the pool leader is based somewhere other than where the real activity happens.
Physical pooling carries an extra layer of exposure here, simply because of volume. Every cross-border interest payment generated by a daily sweep schedule is a fresh candidate for withholding tax analysis. Notional pooling avoids most of that, since the bank credits or debits accounts directly without generating the same chain of intercompany interest flows. Either way, the documentation requirement doesn't change: a clearly written cash pooling agreement, a functional analysis, and a risk assessment, regardless of which structure a group runs.
The landscape keeps shifting, too. The OECD released its Side-by-Side Package on January 5, 2026, introducing a new Side-by-Side Safe Harbour that currently recognizes only the United States as an eligible jurisdiction. Tariff disputes between several major economies add to this, and The resulting disruption to global value chains has added real uncertainty to transfer pricing policy and raised the risk of double taxation.
Basel III's effect on the cost and availability of notional pooling
Basel III liquidity ratios don't automatically let banks net the balances sitting inside a notional pool. In many cases, banks have to calculate their liquidity ratios off the gross value of each individual account rather than the tidy net position the pool produces on paper. That forces banks to hold more liquidity on their own balance sheets just to support the product, which drives up the cost of offering notional pooling to corporate clients.
Not everyone agrees this is as dire as it sounds. Some practitioners argue the banking industry has overstated the difficulty, pointing out that netting has already won regulatory recognition in derivatives, securities, and interbank liquidity management, so there's no structural reason the same recognition couldn't extend to notional pooling given the right treatment. The debate is far from settled: Some industry voices have predicted Basel III could effectively kill notional pooling off entirely, while other practitioners have pushed back hard on that view.
For a treasury team weighing options, notional pooling's cost and availability differ from bank to bank and jurisdiction to jurisdiction, so a treasury team should press a banking partner on how it treats liquidity ratios for a notional pool before signing anything. That same regulatory pressure is a large part of why physical pooling has held onto its position as the most common structure, even in places where notional pooling is technically on the table.
Approaching the decision as a structured evaluation rather than a binary choice
Start with the regulatory map, not a preference. Figure out which jurisdictions in the group's footprint actually permit notional pooling, which ones require physical local accounts, and which ones, like the United States, rule notional pooling out. That map sets the boundaries of what's structurally possible before any question about optimization even comes up.
From there, run governance as the second filter. A decentralized group where subsidiaries need to keep operational and legal autonomy intact will find notional pooling avoids the intercompany loan burden and fund-transfer overhead that physical pooling brings with it. A centralized treasury function that wants a clean audit trail and direct ownership of cash may find physical pooling is the tidier fit despite the extra bookkeeping.
Third, check intercompany and tax compliance capacity honestly. Physical pooling means high transaction volume and real reporting obligations tied to cross-border interest payments, so the finance team has to be resourced for that scale of work. Notional pooling trades volume for scrutiny: fewer transactions to book, but the transfer pricing analysis on the pool leader's remuneration has to hold up under a much closer look.
Fourth, test the banking relationship against the plan. Does the group's primary bank actually offer notional pooling in the hub jurisdiction it wants to use, whether that's London, Amsterdam, or Dublin? Are there subsidiaries locked into regional third-party banks for local reasons, and if so, can those accounts be swept into an overlay or hybrid arrangement instead of left stranded outside the pool?
Fifth, be honest about treasury technology. Hybrid and notional structures running at real scale depend on a TMS capable of automating sweeps, tracking virtual balances, and generating audit-ready intercompany records on demand. Without that infrastructure in place, none of the structural analysis above translates into something a treasury team can actually operate day to day.
Sources
- Currency Consolidation: Notional Pooling vs Cash Concentration
- Notional Pooling: Definition, Benefits, and Process
- What is cash pooling? Intercompany accounting + liquidity management
- What Are Common Transfer Pricing Pitfalls in Cash Pooling?
- Cash Pooling: What Treasury Teams at Multinationals Need to Know Now - Insights | NeuGroup
- 2025 Transfer Pricing year in review