Hedge Accounting Under IFRS 9 for Non-Financial Companies
IFRS 9 lets companies align hedging gains and losses with the actual risks they're managing.
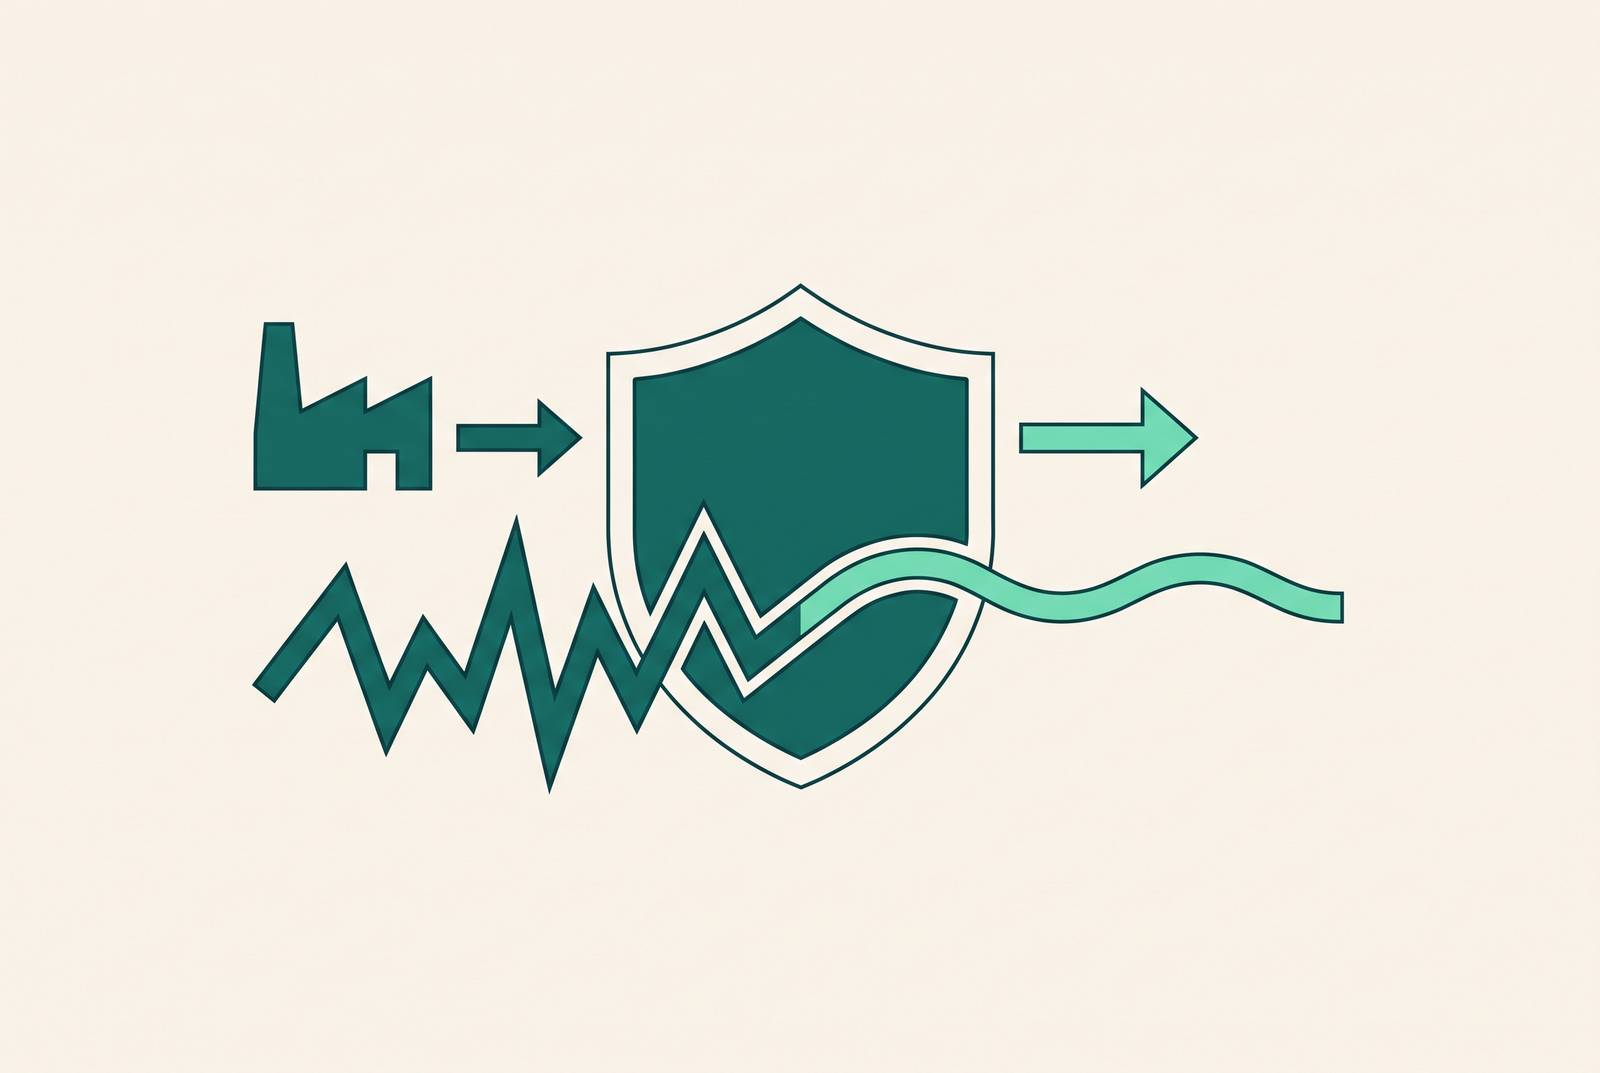
Derivatives sit at fair value through profit or loss on the balance sheet, full stop, unless a company applies hedge accounting. The exposures those derivatives are meant to offset follow entirely different rules: inventories carry at cost, debt is at amortized cost, and forecast transactions, the wheat a bakery plans to buy next quarter or the euros a manufacturer expects to receive, don't appear on the balance sheet at all until they happen. The mismatch that results is mechanical. A swap gains value, that gain hits earnings immediately, and the offsetting loss on the fixed-rate debt it was written to protect sits quietly at amortized cost, invisible until maturity or sale.
None of this reflects what actually happened to the business. But read the income statement in isolation and it looks like the company took a speculative position and got lucky or unlucky, when in fact it did what treasury policy told it to do. Hedge accounting exists to correct that optical distortion, not by changing the economics of the transaction but by aligning the timing of recognition so the offsetting movements land in the same period.
Application remains optional. Nothing in IFRS 9 forces a company to elect hedge accounting for a given relationship. But for companies carrying material commodity, foreign exchange, or interest rate exposure, skipping it doesn't mean skipping the risk, it means reporting earnings that don't reflect the risk management actually taking place. That's the cost of opting out: not economic exposure, but a set of financial statements that lie by omission about how well-hedged the business actually is.
IFRS 9 versus IAS 39 hedge accounting changes, with greater impact for corporates than for banks
IFRS 9 took effect for annual periods beginning on or after January 1, 2018, with its hedge accounting chapter added back in November 2013, well ahead of the broader standard's rollout. That election covers every hedge relationship the company has. There's no picking and choosing hedge by hedge.
Several changes matter more for corporates than for banks: they affect physical commodity flow hedges directly, whereas banks' hedging programs tend to run through interest rate and credit portfolios rather than physical commodity flows. The 80 to 125 percent effectiveness corridor is gone. Under IAS 39, a hedge that was economically sound but drifted outside that narrow band on a technicality failed the test and lost its accounting treatment, sometimes over basis differences too small to matter commercially. Eligible hedging instruments expanded too, now including non-derivative financial instruments measured at fair value through profit or loss, and options became far more workable: a company can designate only the intrinsic value of an option, pushing the time value, the cost of the optionality itself, into other comprehensive income as a cost of hedging.
The bright-line corridor was a liability because of a specific failure mode from the IAS 39 era. After IFRS 13 introduced credit valuation adjustments and debit valuation adjustments into fair value measurement, some hedging instruments picked up CVA and DVA effects that the hedged item never carried. IFRS 9's principles-based test removes that trap entirely, because the standard asks whether an economic relationship exists, not whether a ratio lands inside an arbitrary range. None of this loosens the rigor of hedge accounting. It relocates that rigor from a numerical threshold that could be gamed or accidentally broken toward a substantive demonstration of economic logic. IFRS 9 hedge accounting is described as more principles-based, less complex, and better linked to risk management activities than IAS 39.
The three hedge relationship types and their mapping to typical corporate exposures
IFRS 9 recognizes three hedge relationship types, and each one routes gains and losses through the financial statements differently. The choice of type isn't cosmetic.
Fair value hedges apply when a company is hedging exposure to changes in the fair value of a recognized asset, a recognized liability, or an unrecognized firm commitment, tied to a specific risk that could move profit or loss. The hedging instrument gets remeasured at fair value through profit or loss, and the carrying amount of the hedged item gets adjusted for the same risk, also through profit or loss. Done correctly, the two movements largely cancel out, leaving only the ineffective portion visible in earnings. A company issuing fixed-rate debt and swapping it to floating through an interest rate swap is the textbook corporate case here, whether the company is the debt issuer or simply the holder.
Cash flow hedges cover variability in future cash flows tied to a recognized asset, liability, or a forecast transaction that hasn't happened yet but is highly probable. Here the effective portion of the hedging instrument's gain or loss goes into other comprehensive income, held in what's called the cash flow hedge reserve, until the hedged transaction actually affects profit or loss, at which point it gets recycled into earnings. A bread manufacturer buying wheat futures to lock in the price of a forecast wheat purchase is the clean illustration: if wheat prices climb, the futures gain offsets the higher purchase cost; if prices fall, the futures loss is absorbed against a cheaper purchase. Either way, the income statement shows the price the manufacturer actually planned for. This is, by a wide margin, the hedge type non-financial companies reach for most, since most commodity and FX exposure is in forecast purchases and sales rather than in recognized balance sheet items.
Net investment hedges cover foreign currency risk on a net investment in a foreign operation, with gains and losses parked in other comprehensive income until the investment is disposed of. This one matters specifically to multinationals running subsidiaries that report in a currency other than the parent's.
The type a company selects isn't a matter of preference. It follows from the nature of the exposure, and it decides whether volatility appears in earnings immediately or gets deferred into OCI until the underlying event catches up.
Risk components of non-financial items: the change that opens commodity hedging to corporates
Under IAS 39, a company hedging a commodity supply contract generally had to designate the entire commodity price risk. It could not carve out just the pure price component and leave the rest undesignated. That sounds like a technicality until you look at what it did to effectiveness measurement. Freight costs, storage costs, basis differentials between the hedged contract and the hedging instrument, all of that noise fed directly into the effectiveness test, generating measured ineffectiveness even when the underlying economic hedge was doing what it was supposed to do.
IFRS 9 permits designation of individual risk components of non-financial items, as long as the component is separately identifiable and reliably measurable. The illustration that keeps surfacing in practitioner literature is stainless steel: a company can designate just the nickel component as the hedged risk, leaving processing costs and other elements of the stainless steel price outside the hedge relationship. The wheat futures example works the same way at a simpler level, the forecast wheat purchase is the hedged item, and the futures contract fixes the grain price component specifically, not some blended cost that includes transport or milling.
Whether a component clears the separately identifiable and reliably measurable bar isn't something a company gets to assume. It has to be assessed case by case, against the structure of the relevant market and the specific facts of the contract, so real analytical work has to happen before the hedge is designated. The same logic extends to foreign currency risk components embedded in otherwise non-financial contracts. Put simply, companies that previously had no route to hedge accounting for commodity exposure, or that could only get there through an imprecise full-price designation loaded with basis noise, now have a cleaner path.
Qualifying criteria: what a hedging relationship must demonstrate to be eligible
Three criteria have to be satisfied together, both at inception and continuously afterward. The relationship has to consist solely of eligible hedging instruments and eligible hedged items. Formal designation and documentation has to exist at inception, spelling out the risk management objective and strategy behind the hedge. And the relationship has to meet the hedge effectiveness requirements.
That third criterion carries most of the weight in practice. An economic relationship has to exist: the hedged item and the hedging instrument move in generally opposite directions in response to the same underlying risk. There's no numerical threshold to clear here, but the economic logic has to be demonstrable, not assumed. Credit risk can't dominate the relationship either: if fair value changes driven by the counterparty's or the entity's own credit risk swamp the value movements coming from the underlying economic relationship, the hedge doesn't qualify. And the hedge ratio has to reflect what the risk management strategy actually uses in practice, a company can't deliberately mismatch the ratio just to minimize measured ineffectiveness.
IFRS 9 dropped retrospective effectiveness testing, but the obligation to check prospectively hasn't gone anywhere, companies still have to confirm the relationship continues to qualify and that the hedge ratio remains appropriate. Unlike US GAAP, there's no quantitative effectiveness threshold at all under IFRS 9. The test is qualitative, built around economic relationship rather than a specific number, which sounds more permissive and in principle is, but it demands a much clearer articulation of the reasoning behind the hedge than a numerical safe harbor ever did. Removing the bright line opened up genuine flexibility, but flexibility without a fixed reference point invites judgment calls on dominance of credit risk and on how to prove an economic relationship exists, and auditors scrutinize judgment calls hardest.
Documentation requirements at inception and their evolution
Hedge accounting requires that a relationship be documented when the hedge is put in place. That's a hard line, not a preference.
At inception, documentation has to precisely identify the hedged item and the hedging instrument, the specific exposure, timing, amount, currency, and the exact derivative or instrument being used. It has to lay out the entity's risk management objective and strategy for that hedge specifically. It has to state the designated hedge ratio and the basis for it, tied to how risk management is actually practiced, not adjusted after the fact for accounting convenience. And it has to identify potential sources of ineffectiveness up front: basis differences, credit risk considerations, tenor mismatches, notional amount differences, divergent pricing curves. Flagging these doesn't disqualify the hedge, but they have to be acknowledged before the fact, not discovered later.
None of this is a one-time filing exercise. Documentation has to be updated whenever the hedge ratio gets rebalanced or when the assessment of ineffectiveness sources changes, both of which happen routinely as markets move. Rebalancing itself, adjusting the ratio to keep it aligned with the risk management strategy, doesn't discontinue the hedge relationship. It just requires updated paperwork to match.
IFRS 7 disclosure requirements layer on top of all this, and they apply regardless of whether a company runs its hedge accounting under IFRS 9 or stays on the IAS 39 model. In practice, this has generated real anxiety inside treasury departments, because the disclosures call for forward projections of commodity purchases and sales alongside details of the derivatives hedging them, hedge amounts, hedged rates, the kind of detail that competitors could use.
Accounting for costs of hedging: time value of options and forward points
When a company designates only the intrinsic value of an option as its hedging instrument, rather than the option's full fair value, the time value doesn't disappear from the accounting, it moves to other comprehensive income instead of hitting profit or loss immediately. IFRS 9 treats that time value as a cost of hedging, essentially the premium paid for optionality, and what happens to it next depends on what kind of hedged item is on the other side.
If the hedged item is transaction-related, the accumulated OCI balance gets removed and folded directly into the initial cost or carrying amount of the non-financial asset or liability once the forecast transaction occurs. That's a direct inclusion, folded into the initial cost or carrying amount itself, as described. If the hedged item is time-period-related instead, the accumulated OCI amount gets reclassified to profit or loss over the period the hedged item actually affects earnings.
The same treatment extends to the forward element of forward contracts and to currency basis spreads, both of which can be excluded from the hedge designation and accounted for as costs of hedging through OCI. When a cash-flow-hedged forecast transaction produces a non-financial asset or liability, the accumulated cash flow hedge reserve gets pulled out of OCI and folded straight into the initial cost or carrying amount. Under IFRS 9 that treatment is mandatory. IAS 39 let companies choose between this approach and simply leaving the accumulated gain or loss parked in equity. This corner of the standard is genuinely new relative to IAS 39, and it shows: it's one of the areas where companies have found the practical mechanics harder than the conceptual explanation suggested, and where auditors are still building a settled view.
The macro hedge accounting carve-out under IAS 39
IFRS 9's hedge accounting requirements cover nearly every hedge relationship a company might run, with one specific exception: fair value hedges of the interest rate exposure on a portfolio of financial assets or liabilities, the so-called fair value macro hedge. Companies applying IFRS 9 elsewhere can keep using IAS 39 for these macro hedges under the carve-out written into IFRS 9.6.1.3, and that carve-out stays in place until the IASB finishes its separate macro hedging project.
That project has been moving. In December 2025, the IASB published an Exposure Draft titled Risk Mitigation Accounting, setting out new requirements for how interest rate risk management gets depicted on a portfolio basis under IFRS 9. The proposal is aimed primarily at financial institutions and at industrial companies that designate the relevant hedging relationships and run a sophisticated risk management framework as the standard defines it. Once that project is finalized, IAS 39 gets fully withdrawn. Companies still leaning on it for macro hedges need to start working through the transition implications now rather than waiting for the final standard to land.
For the average non-financial company managing transaction-level or portfolio hedges of commodity, FX, or interest rate risk, none of this changes daily accounting practice. But treasury teams at larger industrials running portfolio-level interest rate risk management should keep an eye on where the Exposure Draft goes, since that's the population it's actually built for.
Operational challenges that arise when applying the standard in practice
IFRS 9 is more permissive than IAS 39 on paper, but permissive and simple aren't the same thing, and companies have generally found the standard harder to implement than its principles-based framing suggested it would be.
The difficulty concentrates in a handful of places. Determining whether credit risk dominates a hedge relationship's fair value movements is a judgment call with no numerical safe harbor to lean on. Accounting for costs of hedging, time value, the forward element, and currency basis, is genuinely new under IFRS 9 and unfamiliar to many treasury and accounting teams. Documentation has to be maintained and updated continuously as hedge ratios shift and markets move, which is an ongoing operational task rather than something completed once and filed away. And prospective effectiveness has to be reassessed as hedge portfolios grow and conditions change, not tested once and forgotten.
Spreadsheet-based processes make all of this worse. Manual designation, manual testing, manual documentation, each one raises operational risk, slows reporting cycles, and weakens audit readiness. And the audit risk compounds over time in a specific way: as auditors build up more experience with IFRS 9's newer mechanics, conclusions a company reached early on under lighter scrutiny can get challenged later, forcing retrospective changes that are far more disruptive than getting the treatment right the first time. Layer the IFRS 7 disclosure burden on top, forward projections of commodity purchases and sales alongside the derivatives hedging them, and treasury teams are dealing with both a heavier workload and a genuine commercial sensitivity problem, since some of what has to be disclosed looks a lot like competitive intelligence handed to anyone reading the filing.
Treasury management systems' support for hedge accounting compliance at scale
Every challenge in the section above traces back to the same root cause: hedge accounting under IFRS 9 asks for continuous, granular, well-documented judgment, and spreadsheets were never built to hold that kind of process together at volume. A treasury team running a handful of interest rate swaps can track effectiveness and documentation by hand. A team running rolling commodity hedges across multiple currencies, multiple forecast periods, and multiple risk components, nickel separated from the stainless steel price, the grain component separated from a bread manufacturer's flour contract, cannot.
They also generate the IFRS 7 disclosure schedules directly from the same designation data, reflecting the more extensive disclosure requirements the IASB introduced by amending IFRS 7 alongside the IFRS 9 hedge accounting chapter, which apply regardless of whether a company uses the IFRS 9 or IAS 39 hedge accounting model.
None of this changes the substance of the standard. It changes whether a company can apply IFRS 9's more flexible, risk-management-aligned model without drowning in the operational detail that flexibility demands, and whether that documentation survives contact with an auditor who has, by now, seen a great many of these relationships tested.
Sources
- Hedge Accounting (IFRS 9) - IFRS Community
- IFRS - IFRS 9 Financial Instruments
- www.pwc.com/ifrs In depth: Achieving hedge accounting in practice under IFRS 9
- IFRS 9 — Financial Instruments
- Need to know Hedge accounting reforms: A closer reflection of risk management
- IFRS 9 hedge accounting: From policy to execution
- A Closer Look Assessing hedge effectiveness under IFRS 9
- IFRS 9: A Practical View of Hedging | Treasury Management International